The Stablecoin Gravity Well


The market is moving toward a world where the dollar becomes the default unit for most on‑chain activity. The rails that move those dollars decide where value accumulates. If you mainly buy coins because you believe a tagline about disrupting one narrow corner of traditional finance, you are not alone. Most people in crypto do the same. The problem is that the money is following a different story.
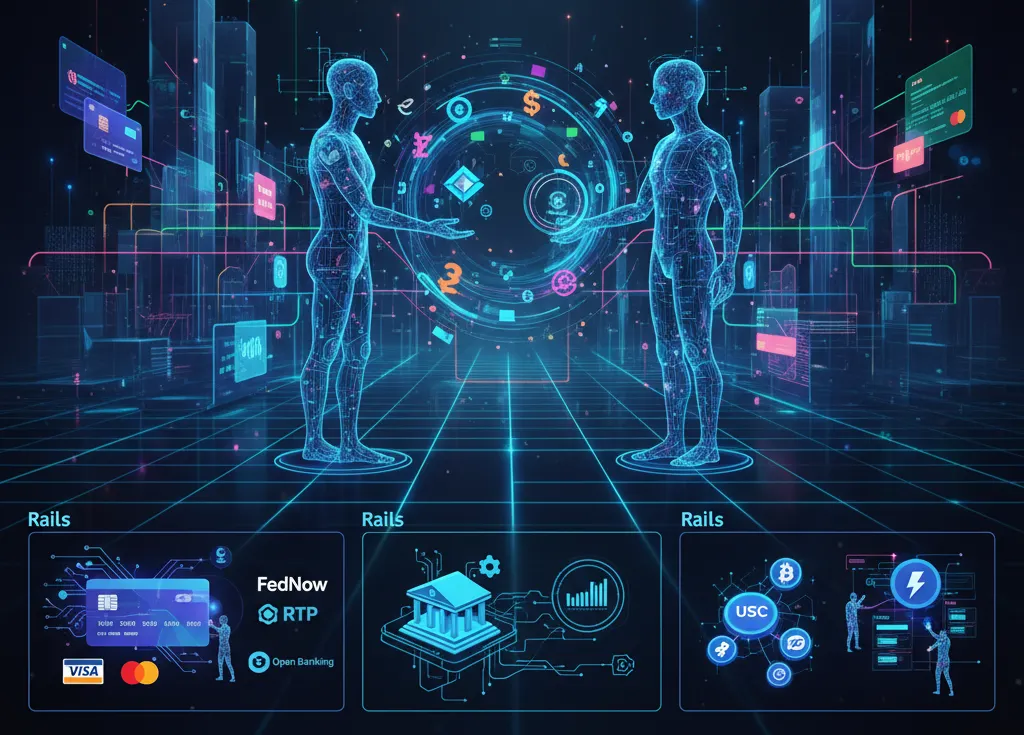
Think about how the internet made information easy to move. Crypto is doing the same for dollars. There are now rails that let a “crypto dollar” burn on one chain and appear on another as the same dollar, not a wrapped imitation. It is like shredding a bill in one city and picking up a fresh bill in another city, with a clerk verifying that the shredding really happened. Those rails are getting faster and simpler, and they can carry instructions so that when the dollars arrive they immediately do something useful, like go into a savings account or pay a bill. This removes a lot of friction between blockchains. It also pulls attention toward places where dollars can act right away.
At the same time, a new kind of base layer is being built with the dollar at its core. Fees are priced in dollars. Foreign exchange between different stablecoins is built in. The stack is designed for payments, settlement, and compliant finance. You do not need to love or hate this direction to profit from it. You only need to accept that it changes which tokens have a claim on future cash flows.
Here is the part most investors miss. When people price everything in dollars, the native coin of a blockchain loses some of its “money premium.” That coin still matters, but mostly as a claim on blockspace and on the fees that flow through the system. Every time someone pays, swaps, deposits, or redeems, they use the chain’s resources. If the chain turns those arrivals into useful multi‑step actions with minimal hassle, it keeps more of the economic value. If the chain acts like a pass‑through, the value leaves as quickly as it arrived. Narratives about disrupting a specific industry do not change this math. Dollars follow the path of least friction. Prices follow places that take a cut of that flow.
When dollars move, who gets paid in a way that reaches the token? Some tokens have clear “pipes” from revenue to holders. That can be a fee that is denominated in stablecoins and used to buy and burn the token. It can be a share of protocol income routed to stakers. It can be sustained demand for the token to secure the network when activity rises. Other tokens have no pipe at all. The project might talk about partnerships and pilots and future disruption, yet there is no mechanism that connects higher dollar volume to token value. In a dollar‑denominated future, that difference matters more than any tagline.
Get Walter Blueu’s stories in your inbox
Join Medium for free to get updates from this writer.
You do not need to master on‑chain analytics to spot the early signs. Follow the defaults. Wallets and bridges decide where ordinary users end up because most people tap whatever the app suggests. Merchants and payment processors choose routes that settle predictably and reconcile cleanly. Credit and trading venues gravitate to low fees with high reliability. When a particular path becomes the default in a few major tools, volume tends to cluster there. Price impact shows up later. If you wait to see it in charts of total transactions or “unique users,” you are late. Those totals mix real economic activity with noise. In this cycle the signal is dollar‑weighted settlement and the quality of the take rate, the slice of those dollars the protocol keeps as real revenue.
Thinking through this lens leads to different choices. It favors the “toll booths” that charge in dollars and push value to the token in a way that cannot be waved away. It favors execution layers that keep order flow on their turf by making it easy for dollars to arrive and immediately do work. It favors middleware that becomes the standard route for moving value between places. It asks you to be skeptical of assets that still depend on being used as money someday. When users already have something that acts like money and keeps its value stable, they use that. The native coin needs another reason to exist.
This shift does not mean giant risks have disappeared. Stablecoins still rely on banking access, operational reliability, and regulator tolerance. A depeg is rare, not impossible. Centralized controls can freeze funds in some situations. The rails that move dollars make switching easy. If a venue tries to extract too much rent, volume can reroute in days. The best trades will live along the rails and at the endpoints that convert flow into margin.
If you hold a bag because you believe it will disrupt one narrow industry, you can still use that story, but treat it as optional upside. Ask yourself whether people in that industry would rather hold a volatile token or hold dollars and use that token’s chain only when necessary. Most of the time they will choose dollars. That means your coin needs a plan to capture value when dollars show up. It needs a way to take a share of real activity and return it to holders. Without that, you are paying for a dream while other projects collect the fees.
The simplest mental model is this. Stablecoins are the magnet. They pull liquidity toward the places where they can act immediately. Your job is to own the rails that move the dollars and the venues that turn arrivals into cash flows. When you think about a token, ignore the mission statement for a moment and imagine dollars flowing through pipes. If you cannot find the pipe that leads from flow to the token, keep your money. If the pipe is obvious and hard to copy, pay attention. Rotating early into those positions beats arguing on social media about which chain is philosophically pure.
Think about how the internet made information easy to move; crypto is doing the same for dollars, and that’s exactly why stablecoin adoption is the on‑ramp for institutions. For broker‑dealers and market makers dollar‑stable settlement lets them fund trades, margin accounts, and client flows 24/7 without wire cutoffs or FX slippage, while moving collateral between venues in minutes instead of days. For asset managers stablecoins simplify LP subscriptions and distributions, park dry powder in a dollar unit of account, and shuttle capital across exchanges, custodians, and chains with predictable fees and audit trails. Corporate “digital asset treasury” teams use stablecoins as working capital to pay vendors, payroll, and counterparties on weekends, and to sweep idle balances into on‑chain cash equivalents, tightening cash cycles without taking native‑token volatility. ETFs and their authorized participants benefit when creations and redemptions can be funded in stablecoins, because arbitrage capital rotates faster, spreads tighten, and inventory can be rebalanced continuously even when banks are closed.
Across all of these, canonical cross‑chain rails (burn‑and‑mint rather than wrapped IOUs) reduce settlement risk and unify liquidity, while programmable settlement lets arriving dollars auto‑route into custody, hedges, or fee payments the instant they land. The through‑line is operational: firms already think in dollars, account in dollars, and report in dollars, so stablecoins make crypto networks feel like familiar financial plumbing, just faster, programmable, and always on.
A dollar‑denominated future does not end speculation. It clarifies it. Prices will track who gets paid when dollars move. Narratives will still drive attention, but cash flow will do more of the heavy lifting. If you want an edge in this new crypto landscape, stop treating taglines as truth and start tracing the path of dollars from point A to point B. The gravity well is the dollar. The trade is to stand where it passes and to own what takes a cut as it goes by.