College Signing Day Has Passed. Now What?

Two weeks ago, students, counselors, and families recognized College Signing Day, an amazing annual event spearheaded jointly by #ForeverFirstLady Michelle Obama’s Reach Higher Initiative and Better Make Room, which celebrates high school seniors’ decision to pursue either some form of post-secondary enrollment or a role in the military. In practical logistical terms, for many students pursuing a post-secondary credential, this meant celebrating that students had sent in their deposits to formally commit to their future colleges.
We at Edquity love College Signing Day from a culture-building standpoint; students should celebrate — and be celebrated for — their achievement of checking off another major milestone on their journey to a post-secondary credential or a military career.
It’s important to remember, however, that College Signing Day and students’ financial commitments to their schools aren’t a finish line. Rather, the financial journey for students is truthfully just beginning.
The next milestone? Getting through the summer financially and showing up to college in a position to financially succeed.
Every year, anywhere from 10 to 40 percent of students succumb to a phenomenon known as the summer melt: where students intending to matriculate to college fail to enroll in the fall. There are a whole host of nuanced issues, not all of them financial, that can induce this terrible outcome. Those that are financial, however, can be devastating.
Our mission at Edquity is to support students through every financial obstacle on the long road to college graduation. In that spirit, here are a few of the financial planning pitfalls that Edquity specifically tries to help students avoid as they prepare for their transition from high school to college:
Failure to Understand Financial Gaps
Financial aid awards are extraordinarily confusing. uAspire and New America, two wonderful organizations serving and advocating on behalf of students, have documented some of the more sinister ways this can be true, which include everything from omitting cost information to failing to contextualize cost information to using inconsistent and confusing language to represent and characterize financial aid.
As students and families plan for college, it’s important to have a clear sense of available grant aid, projected work obligations and what this means from a time management standpoint, and intentions around borrowing. In doing so, students need to beware of the following:
- Terms such as “self-help grant” (which is a layman’s term for “the student is paying” for it).
- Representation of a remaining balance that includes subsidized, unsubsidized, Perkins loans, or, even worse, Parent PLUS loans in the calculation. Loans are borrowed and should not be confused with grants as free aid to plug gaps.
- Viewing Parent PLUS Loans as a sure thing to plug a gap, as parents in many cases aren’t willing to borrow on a student’s behalf or fail to pass a credit check even when they are willing to do so.
- Any representation of Work-Study. The reality is that, even if this is listed on an award letter, it nevertheless might not be available for a variety of reasons. Students should get in touch with their financial aid office about Work-Study because it’s possible a student wouldn’t be able to rely on this due to the available funding pool (or lack thereof) at the school.
(You can use Edquity’s financial aid feature to clarify your gap based on what’s written on your award letter — regardless of the bizarre nomenclature that may be listed.)
Failure to Understand Financial Gaps…in a Way That Accounts for the Student’s Personal Indirect Costs
A horrible truth is that many colleges fail to include indirect costs in their award estimates. And those that do often fail to accurately represent the reality experienced by students. As a student is assessing her gap to determine assumptions around work and how to draw down loans, it’s critical to calibrate these decisions to her gap inclusive of her indirect costs. While the indirect cost universe can be similar across the board, how a student will experience that universe can vary significantly. In general, this universe often includes:
Get David Helene’s stories in your inbox
Join Medium for free to get updates from this writer.
Upfront Costs
- Books and supplies
- Move-in/furnishing expenses related to on- or off-campus living
- Clothes
- Insurance
- Transportation
- Laptop/Tablet (if necessary)
At-College Expenses
- Rent & Utilities (if off-campus or at home)
- Groceries or Miscellaneous Food
- Cell Phone Plan
- Personal Care (think haircuts, toiletries, cosmetics)
- Transportation
- Subscription Services (think Netflix)
- Support to One’s Family (if a student has very real financial obligations at home)
- Eating Out & Social Expenses
- Clubs, Extracurriculars, and Events
- Miscellaneous Seasonal Expenses (think Mom’s birthday)
- Coffee and Other Drinks
- Emergencies
It’s important to understand if and which of these costs may be relevant to an individual student and how these costs could differ depending on personal consumption habits and where the college is located.
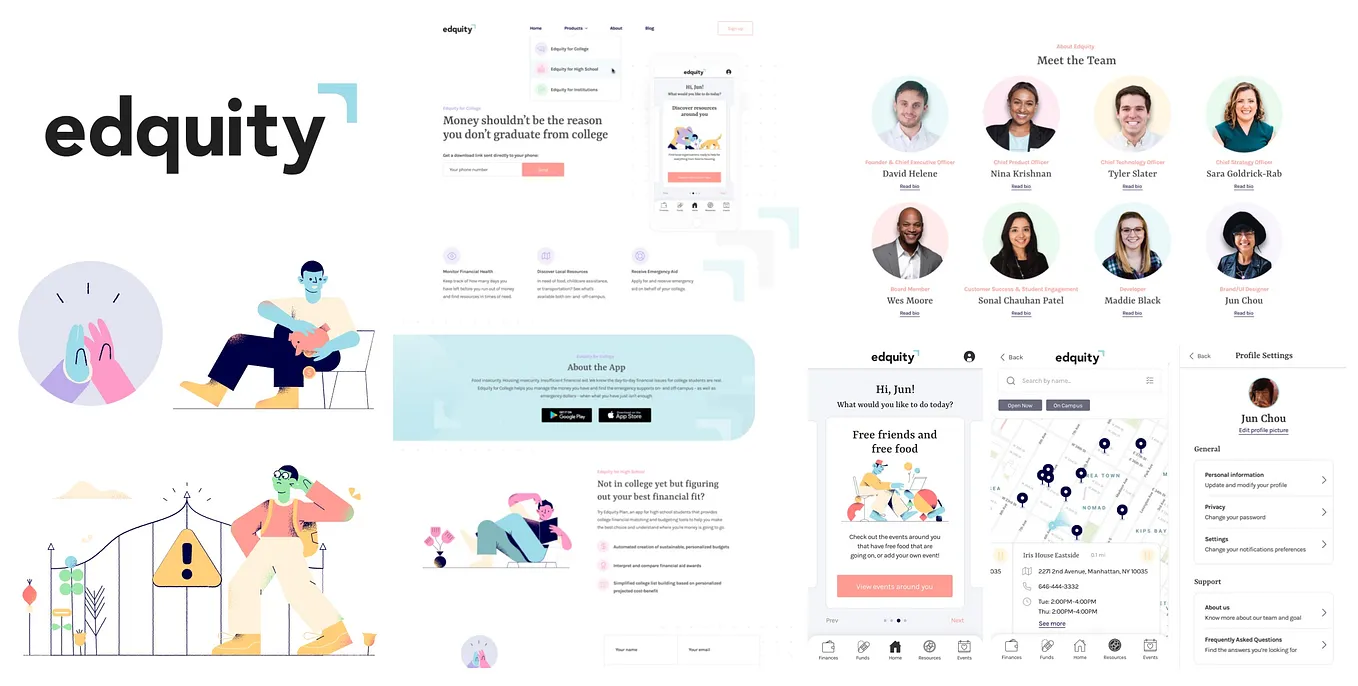
I won’t lie: this is a complicated exercise. When I was in the classroom working with students at my former non-profit, we tried to map this out in excel, and it was extremely difficult to do so in a personalized way that accounted for all individual circumstances and the geographic cost of living. The good news is students can use Edquity to build these budgets in a way that takes into consideration individual financial aid awards, personalized needs, and the school’s geographic cost of living to provide for understanding around real gaps and to allow for optimizing working and borrowing decisions.
In lieu of Edquity, student can look into resources like CNN Money’s Cost of Living Calculator (for major cities) to try to understand how costs in their current city might look in others.
Lack of Understanding Around When Financial Aid Will Be Available
While a financial aid award letter tells you what you’ll have access to, it doesn’t tell you when. Unfortunately, timing matters a lot. For most students, tuition payments are due in August. Books and supplies similarly need to be purchased then as well. Yet, students often don’t have access to their financial aid to pay for this until September or even October. It’s important to figure out what expenses need to be paid when and what resources will be available to do so, as this type of analysis can also help inform whether a tuition installment plan might be necessary or whether access to alternative forms of credit beyond federal loans may be necessary to pay for certain upfront (or other) costs.
Seeing Assumptions Around Work Not Pan Out
Over 70% of college students work. As we know, managing work and school can be unbelievably challenging, particularly if a student is working more than 20 hours per week (which, unfortunately, far too many students need to do, with 40% working more than 30 hours per week). If a student is intending to rely on work to plug any gaps, we recommend beginning to identify how many hours per week you’ll need to work, and, on top of that, to start doing homework on where that work might be available. Too many students find themselves (and again, for no fault of their own):
- working more than they’d anticipated,
- working jobs that have unpredictable and inflexible work hours, leading to conflicts with class or a general inability to complete schoolwork,
- and/or unable to find the work they assumed they’d find altogether.
We implore students to do whatever they can to get ahead of these issues as much as possible. This could include researching job sites to scout out part-time work around campus, reaching out to current students to get an anecdotal lay of the land with regards to the off-campus job market, and contacting the financial aid office directly to get a sense of what on-campus work might be available. While we unfortunately can’t yet recommend local employment resources, Edquity can help map out some of the risks one can run into with regards to work.
* * *
We know these are hard challenges, and we empathize deeply. If you’re going through this process, it’s important to remember that you’re awesome for getting into college in the first place, you deserve to succeed, and any financial challenges you’re experiencing related to college are not your fault.
We at Edquity are here for you, so if you have any questions, e-mail us at hello@edquity.co and we’ll do our best to help.